Quick answer
Farmers and agribusinesses use fast loans to buy seed, fertiliser and fuel ahead of planting, repair or replace machinery at critical times, buy livestock and carry costs until harvest or sale. Farm and residential property can secure loans from $20k to $5m with no valuation, and approval within the hour is common.
Key points
- Inputs are paid months before harvest income
- Machinery breakdowns at planting or harvest are critical
- Farm property can secure larger amounts quickly
- Seasonal income patterns are normal to lenders
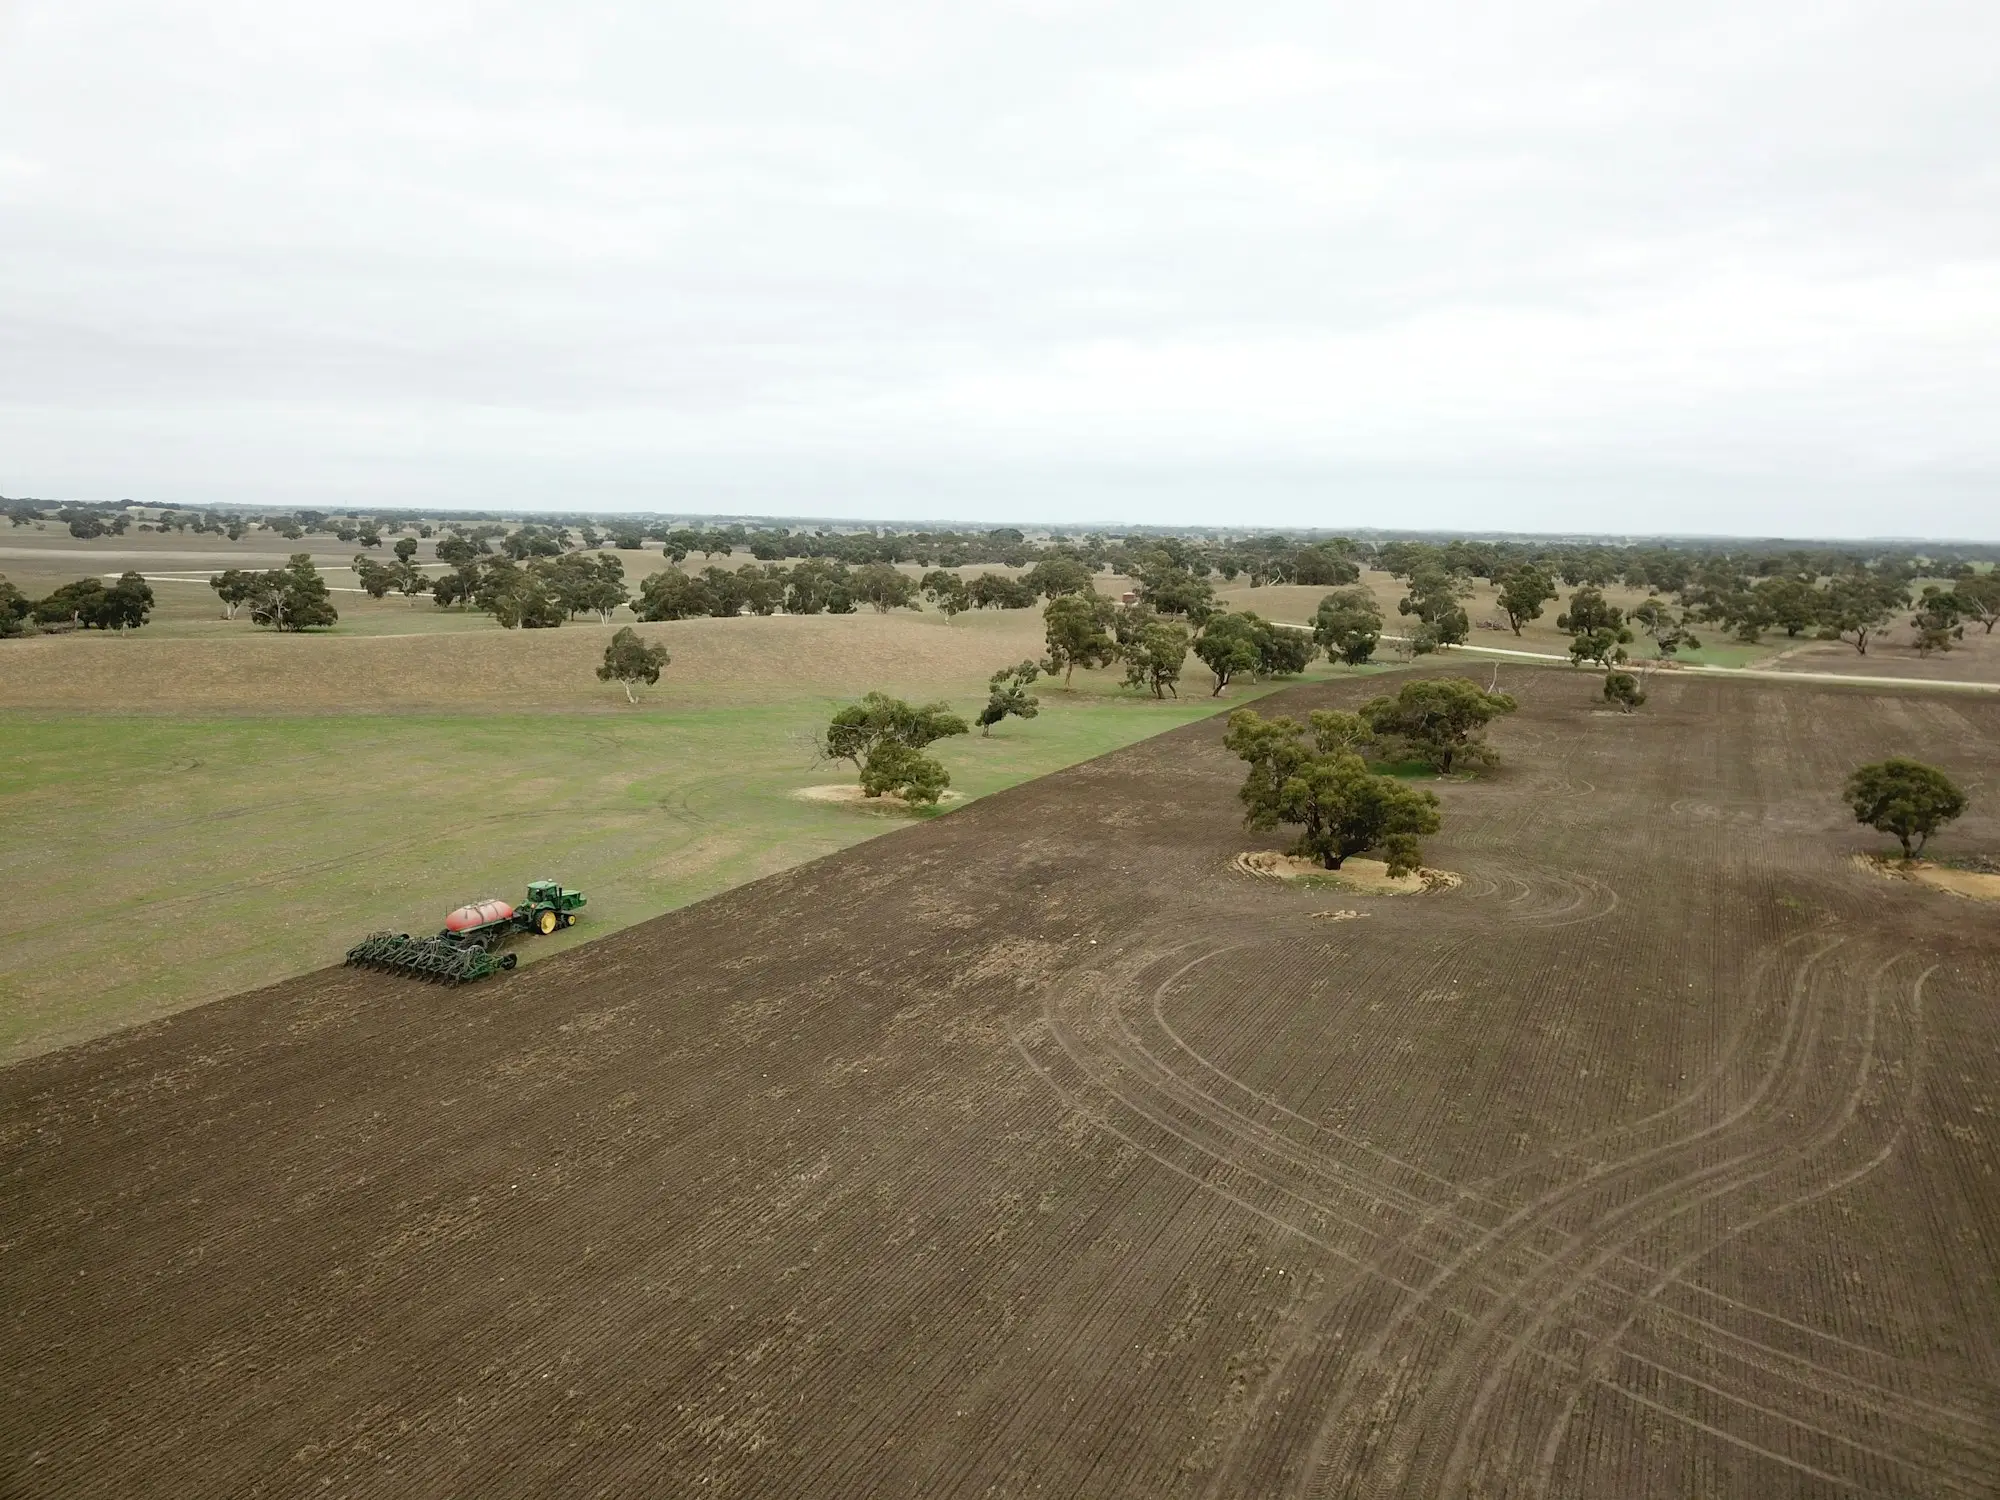
Farming is the original cash flow gap. Seed, fertiliser, chemicals, fuel and labour are paid for months before a crop is harvested and sold. Livestock is bought, fed and cared for before it goes to market. Machinery has to work when the season says so, not when the workshop is free. And weather can change everything in a week.
The usual pressure points
- Inputs ahead of planting: seed, fertiliser, chemicals, fuel.
- Machinery breakdowns at planting or harvest.
- Livestock purchases when prices or opportunities are right.
- Carrying costs until harvest or sale.
- Drought, flood and fire disruption.
How lenders read a farm business
Assessors look at the seasonal pattern of income from grain, livestock or produce sales, input purchases and existing machinery finance. Seasonal swings are expected. Farm and residential property can support property-secured loans from $20k to $5m with no valuation needed. Approval within the hour is common.
Ready to move? Check your options in 60 seconds. Nothing is sent to a list of lenders.
What the next 24 hours can look like
| Step | How long it usually takes | The common hold-up |
|---|---|---|
| Tell us what you need | A minute | Rounded or guessed figures |
| Talk it through | A short call within minutes | Missed calls |
| Get approved | 15 minutes to an hour for most clean profiles | Statements that are hard to access |
| Sign documents | A few hours | A co-owner or guarantor who is unavailable |
| Receive funds | As little as 24 hours from enquiry | Late-day payment cut-offs |
Matching the need to the loan
| Need | Usually fastest |
|---|---|
| Machinery repair at harvest | Unsecured short-term funding |
| New or used machinery | Fast equipment finance |
| Inputs before planting | Short-term or property-secured funding |
| Livestock purchase | Property-secured, interest prepaid or added |
Speed tips for farmers
- Have last season’s sales receipts visible in your statements.
- Keep machinery details and repair quotes handy at critical times.
- Know which entity owns which land, especially with family trusts.
- Arrange funding before the season starts, not halfway through.
A worked example (illustrative)
A grain grower near Wagga Wagga has a header gearbox fail in the first week of harvest. The repair costs about $36,000 and the dealer will start immediately if paid. The grower shares the quote and statements at dawn, is approved within the hour and the header is back in the paddock two days later, before rain arrives.
Check support programs too
Government and state programs, including disaster support and concessional loans, may help in tough seasons. Use them alongside fast funding, which bridges the timing while grants and claims are processed.
Family land, family signatures
Farm property is often held across generations and entities. If the land you would offer as security has several owners, talk to them early. Everyone on the title signs, and that conversation is far easier before harvest than in the middle of it.
Documents that speed things up
Have these within reach and you remove the usual causes of delay:
- Business bank statements covering last season
- Machinery quotes or repair invoices
- Property details and ownership
- Livestock or crop contracts
- Photo ID and ABN
Where the time usually goes
These are the things that most often turn a same-day answer into a three-day one:
- Land held across several family entities
- Owners unavailable during harvest
- Unclear machinery ownership
- Arranging funding mid-season
A note on the enquiry form
Most delays we see trace back to something that changed after the first call: the amount went up, the turnover turned out lower, a second director appeared or the property was in a trust. None of these are deal-breakers. They just cost time when they arrive late. Put the real picture in the form, and the assessment can be done once, properly and quickly.
Before you go
- Inputs are paid months before harvest income
- Machinery breakdowns at planting or harvest are critical
- Farm property can secure larger amounts quickly
- Seasonal income patterns are normal to lenders
How the 24-hour clock works here
Fast does not mean careless. Every loan still gets a proper look at how the business trades, who owns it and how the money will be repaid. The difference is that we do the looking quickly and in parallel. Bank statements can be read in minutes once they are shared, property loans do not wait on a valuation, and documents are signed electronically. Approval within the hour is common, and funding within 24 hours is possible when every party signs promptly.
Check your options now
Tell us what you need and when you need it by. There is no credit check to enquire, nothing is passed around the market, and a human being, not an algorithm, reads it. Accurate answers on the form are the single biggest thing you can do to speed things up. See if you qualify.
Frequently asked questions
Can a farmer get a fast business loan?
Yes. Farm income in bank statements supports unsecured funding, and farm or residential property can secure larger amounts.
Can I fund a header or tractor repair at harvest?
Yes. With the repair quote and statements, approval within the hour is common.
Can rural land be used as security?
Often, yes, along with residential property, with no valuation needed.
What about drought or disaster?
Check government and state support programs, and use fast funding to bridge timing gaps.
Start the clock right here
The same 60-second enquiry, on this page. No credit check to enquire, and a real person picks it up fast.